Compared with much of Asia, Malaysia allows foreigners to own property relatively freely — including full ownership of most condominiums and serviced residences, in their own name. That openness, combined with prices that remain reasonable for a capital city and a large English-speaking population, is a big part of why prime Kuala Lumpur draws steady interest from overseas buyers.
Foreigners can buy and own most residential property in Malaysia outright, without needing a local partner or company for a standard condominium purchase. The main conditions are a minimum purchase price (set by each state) and state authority consent, which is a routine part of the conveyancing process for eligible properties.
The single most important rule to understand is the minimum price threshold. Each Malaysian state sets a floor on what a foreigner may pay for a property, partly to keep entry-level housing available to locals. These thresholds differ from state to state and are reviewed from time to time.
For most of Kuala Lumpur, the minimum a foreigner can pay is RM1 million — the level that has applied in the Federal Territory, and as a national floor, since 2022. Other states set their own minimums and some are higher. As a guide to the current position:
| State / area | Minimum for foreign buyers |
|---|---|
| Kuala Lumpur | RM1,000,000 (strata & landed) |
| Selangor | RM2,000,000 in Zones 1 & 2; RM1,000,000 in Zone 3 — strata or strata-titled landed only |
| Penang (island) | RM1,000,000 strata; RM3,000,000 landed |
| Penang (mainland) | RM500,000 strata; RM1,000,000 landed |
| Johor | RM1,000,000 (strata & landed) |
Figures current at the time of writing and reviewed periodically by each state — always confirm the number that applies before you commit. We share the figure current for your purchase on enquiry.
The practical implication for prime KL is simple: the new-launch residences most overseas buyers look at sit comfortably above the RM1 million threshold, so eligibility is rarely the obstacle.
Some categories are off-limits or restricted for foreign buyers:
For most overseas buyers looking at new-launch condominiums and serviced residences in Bangsar or Damansara Heights, none of these apply — but they are worth knowing.
Beyond the price of the home, budget for transaction costs — and one changed significantly for 2026. From 1 January 2026, the stamp duty on the transfer of residential property (the Memorandum of Transfer, or MOT) for non-citizen individuals and foreign companies rose from 4% to a flat 8% of the property value. Malaysian citizens still pay a tiered rate (1% to 4%); the flat 8% applies to foreign buyers, and Malaysian permanent residents are excluded.
The main buying costs to plan for:
As a rough illustration, a foreigner buying a RM1,000,000 condominium in KL would pay about RM80,000 in MOT stamp duty, plus legal fees and — if financing — 0.5% on the loan. Exact figures depend on the property, your financing and any developer incentives, so confirm them with your lawyer before committing.
If you sell later, Real Property Gains Tax (RPGT) applies to any profit. For non-citizens the rate is higher in the early years and lower once you have held longer; as a guide it has been 30% on gains disposed within the first five years and 10% from the sixth year onward, but confirm the current rate with a tax adviser at the time of sale.
Malaysian banks do lend to foreign buyers. As a guide, a non-resident can often borrow up to around 70% of the price, though many banks are more conservative and the exact margin depends on the bank, your income profile, your nationality and where you are based. Many overseas buyers combine a local loan with their own funds. It is worth getting an indication of what you can borrow early, so your shortlist matches your budget.
Buying property does not by itself give you the right to live in Malaysia. If longer stays are your goal, the Malaysia My Second Home (MM2H) programme is a separate long-stay scheme with its own financial and property requirements, which are set nationally and updated periodically. Property can be part of an MM2H plan, but the two are distinct — treat them separately and take current advice on MM2H specifically.
As a developer-appointed sales agency, we guide buyers — including those still abroad — through the whole path: shortlisting suitable residences, arranging virtual and in-person viewings, confirming the current price threshold and eligibility, and coordinating with the developer and your lawyer through to handover. The starting point is a short conversation about what you are looking for.
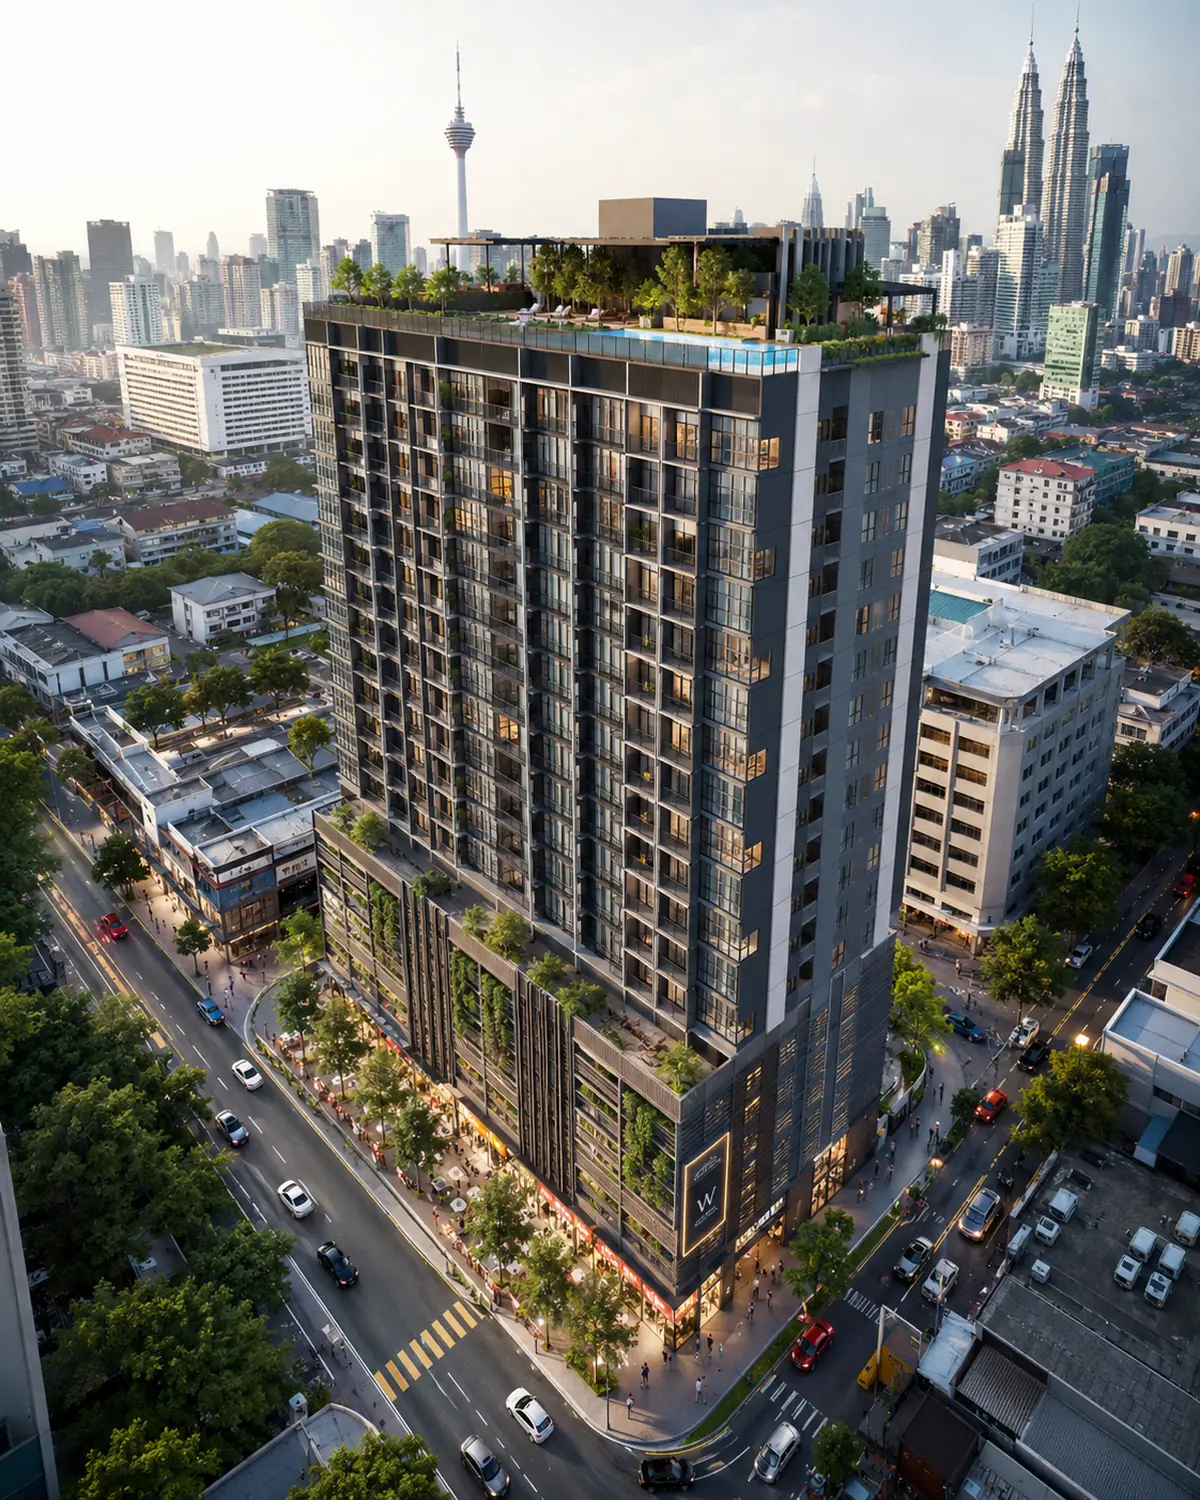
Prime-KL new launches, comfortably above foreign-purchase thresholds.
Meet Your Agent
Your Mont Kiara · Bangsar · KLCC property specialist
For over five years, I’ve helped both Malaysians and international buyers settle into Kuala Lumpur’s most sought-after addresses. My promise is simple: honest guidance, real numbers, and none of the pressure.
From your very first viewing to the day you hold your keys — and long after handover — I’m the agent you’ll be glad you called.
Tell us where you are based and what you are looking for. We will confirm eligibility, share suitable residences, and guide you through every step.